What Is a Land or Development Loan?
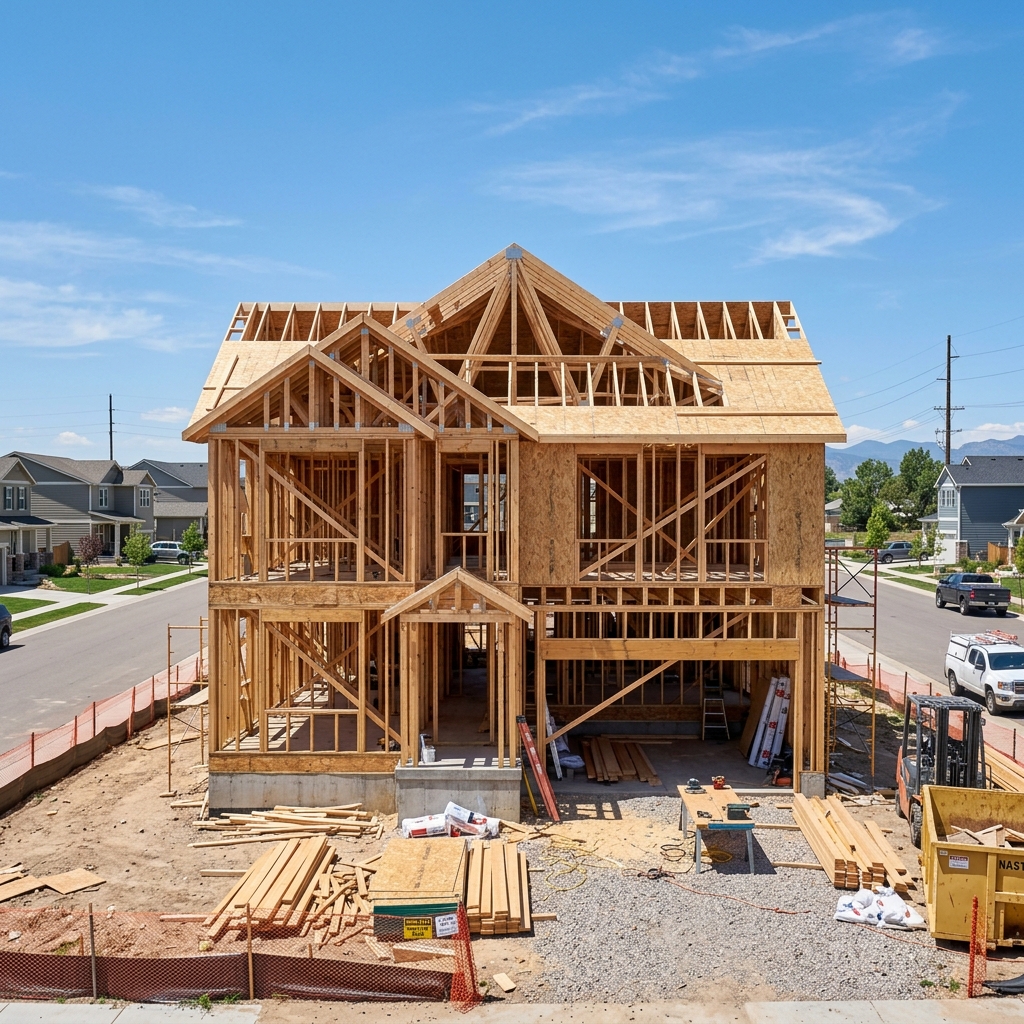
A land loan finances the purchase or refinance of land, while a development loan funds the horizontal work — clearing, grading, utilities, and roads — that turns raw land into build-ready lots. Both are short-term, asset-based loans secured by the land itself and underwritten on its value, stage, and the borrower's plan, for business or investment purposes only. Land is the hardest real estate to finance because it produces no income and carries the most risk for a lender.
How Do Land & Development Loans Work?
Land financing is sized against the land's value and, critically, its stage of development — raw, entitled, or development-ready. Because vacant land generates no cash flow and sells slower in a downturn, lenders require larger down payments and charge more than they would on an income property. The loan is repaid by your exit: building on the land, selling it, or refinancing into a construction loan. A credible, well-defined exit is the single most important part of the request.
Land Loan Rates, Points & Fees (2026)
Most private land and development loans carry an interest rate in the range of about 9% to 14% in 2026, with pricing rising as the land gets rawer and the plan less defined. Leverage moves inversely: raw land is commonly capped near 50% loan-to-value, while entitled land with approved zoning or permits can reach up to about 65%. Origination points and required reserves vary by lender and by how much execution risk the parcel carries.
Land Financing by Stage
Raw / Unentitled Land
Raw land is the hardest to finance and the most conservative in leverage — often up to about 50% LTV, meaning a 50% down payment — because it has no entitlements and the slowest resale.
Entitled Land
Once zoning, approved plans, or permits are in place, the parcel is far more financeable, and leverage can reach up to about 65% because the path to a buildable project is clear.
Development / Construction-Ready
When the plan is to build, land financing is often structured together with the construction loan, and existing land equity can count toward your required contribution rather than more cash.
Land & Development Loan Requirements — Do You Qualify?
Land approval depends on the parcel's stage, a credible exit, and your plan, with experience and liquidity affecting leverage. Lenders generally look for: a clear exit — build, sell, or refinance; a larger down payment, typically 35% to 50% or more depending on the land; zoning, entitlements, or a development plan that de-risks the parcel; reserves and liquidity; and, on development deals, relevant sponsor experience.
Land Loan Scenarios
Common land scenarios are acquiring entitled lots to build on, financing horizontal development to make raw land build-ready, a cash-out refinance on land owned free and clear to fund entitlements or the next deal, and rolling land acquisition and construction into a single financing when the build is ready to start.
Land Financing vs. Bank Financing
Choose a bank land loan when you have strong financials, entitled land, and time, and want the lowest rate; choose private land financing when the parcel is raw, the timeline is tight, or a bank has declined it. Because most banks limit or avoid land lending, private capital is often the only practical way to finance an acquisition or horizontal development.
Pros and Cons of Land & Development Loans
The main advantages of private land financing are access to capital banks avoid, speed, and the ability to count land equity toward a future build; the main drawbacks are lower leverage, higher cost, and larger down payments than income-producing property. Land financing rewards a clear entitlement path and a defined exit.
How to Choose a Land Lender
The best land lender is one of the smaller pool that actually finances land at your parcel's stage and in your market — raw, entitled, or development-ready — with leverage and a term that fit your plan. Bring Capwell the scenario once, and we match the parcel with lenders likely to fund it so you can compare real terms.